Jiacheng Zhang
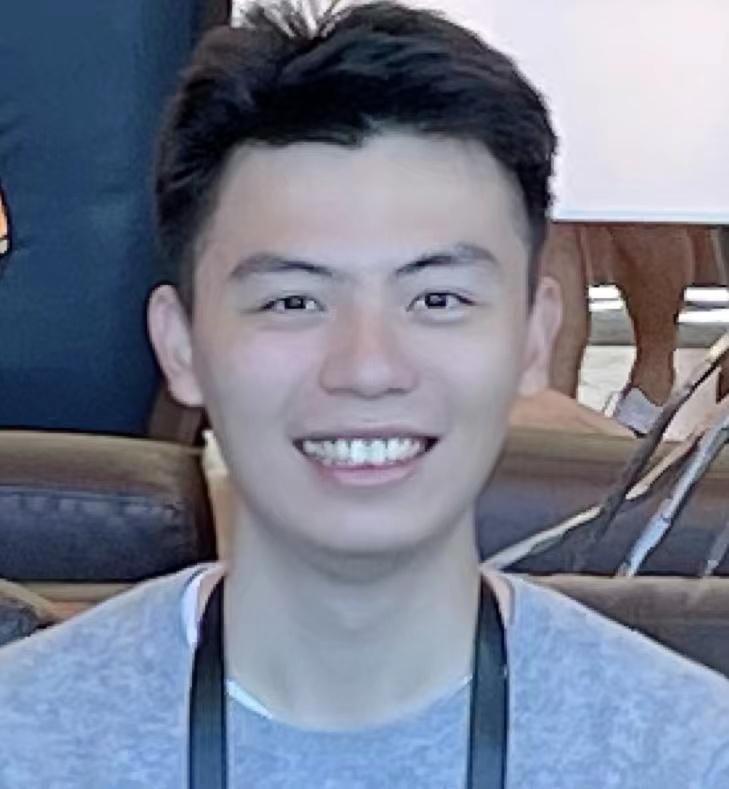 |
I am an Assistant Professor at Department of Statistics and Data Science, The Chinese University of Hong Kong. Previously, I was a postdoctoral researcher in Industrial Engineering & Operations Research Department at Univeristy of California, Berkeley advised by Professor Xin Guo. I obtained my Ph. D. in the Department of Operations Research and Financial Engineering at Princeton University supervised by Professor Daniel Lacker and Professor Mykhaylo Shkolnikov in 2021. Prior to these, I received my bachelor's degree in Math from Tsinghua University in 2016. I can be contacted at jiachengzhang [at] cuhk [dot] edu [dot] hk My research focus lies in the theory of probability and stochastic optimization. I have worked on stochastic partial differential equations, especially Mckean-Vlasov type equation, partial differential equations, mathematical finance like stochastic portfolio theory and stochastic volatility modeling in the past few years. |
Papers
Dynamics of observables in rank-based models and performance of functionally generated portfolios with Sergio A. Almada Monter and Mykhaylo Shkolnikov
Annals of Applied Probability (2019)Inverting the Markovian projection, with an application to local stochastic volatility models with Daniel Lacker and Mykhaylo Shkolnikov
Annals of Probability (2020)Superposition and mimicking theorems for conditional McKean-Vlasov equations with Daniel Lacker and Mykhaylo Shkolnikov
Journal of the European Mathematical Society (2022)Stationary solutions and local equations for interacting diffusions on regular trees with Daniel Lacker
Electronic Journal of Probability (2023)Agency problem and mean field system of agents with moral hazard, synergistic effects and accidents with Thibaut Mastrolia.
Journal of Optimization Theory and Applications (2025)Optimization frameworks and sensitivity analysis of Stackelberg mean-field game with Xin Guo and Anran Hu
Submitted.On time-consistent equilibrium stopping under aggregation of diverse discount rates with Shuoqing Deng and Xiang Yu
Mathematics of Operations Research (2025)Deep Learning for Population-Dependent Controls in Mean Field Control Problems with Gökçe Dayanıklı and Mathieu Laurière
Proceedings of the 23rd International Conference on Autonomous Agents and Multiagent Systems. (2023)Ito's formula for flows of conditional measures on semimartingales with Xin Guo
Electronic Journal of Probability. (2025)Major-Minor Mean Field Game of Stopping: An Entropy Regularization Approach with Xiang Yu, Keyu Zhang, Zhou Zhou
SIAM Journal on Control and Optimization. (2026)Dimension-free error estimate for diffusion model and optimal scheduling with Valentin de Bortoli, Romuald Elie, Anna Kazeykina, Zhenjie Ren
Transactions on Machine Learning Research (2026)Continuous-time mean field games: a primal-dual characterization with Xin Guo, Anran Hu and Yufei Zhang
Submitted.Deep Signature Approach for McKean-Vlasov FBSDEs in a Random Environment with Ruimeng Hu, Botao jin and Mathieu Laurière
Submitted.
Teaching
Princeton University (TA)
a. ORF 309 Probability and Stochastic Systems
b. ORF 527 Stochastic Calculus
c. ORF 526 Probability Theory
University of California, Berkeley
IND ENG 263B Applied Stochastic Process II as an co-instructor together with Professor Xin Guo.
The Chinese University of Hong Kong
a. STAT 2001 Basic Concepts in Statistics and Probability I
b. STAT 3007 Introduction to Stochastic Processes
c. RMSC 5102 Simulation Techniques in Risk Management and Finance
Award
School of Engineering and Applied Science Award for Excellence (2021)
This award is given to SEAS advanced graduate students who have performed at the highest level as scholars and researchersMember of Tsinghua Xuetang Training Program for excellence in academy (2012-2016)
National Scholarship (2012)